Call for papers
You can download the call for papers in PDF format here
The global financial crisis of 2008–2009 profoundly reshaped our understanding of financial market stability, systemic risk, and the limits of traditional risk-management and econometric frameworks. More recently, the COVID-19 pandemic triggered an unprecedented combination of financial, economic, and geopolitical shocks, leading to sharp increases in market volatility, liquidity stress, and uncertainty. These disruptions have been followed by persistent inflationary pressures, rapid changes in monetary policy and interest-rate regimes, energy and commodity-market shocks, and heightened geopolitical tensions. Financial markets are also increasingly exposed to new sources of uncertainty associated with rapid technological transformations, the development of artificial intelligence, and the growing speed, automation, and interconnectedness of global financial systems. These successive and overlapping shocks highlight the need for new approaches capable of capturing the nonlinearities, structural changes, heterogeneity, and complex dependencies that characterize modern financial markets.
At the same time, financial markets are undergoing a profound data and technological transformation. The availability of massive high-frequency and ultra-high-frequency datasets, order-book information, transaction-level data, news and textual data, alternative data, and other non-traditional sources has created unprecedented opportunities for understanding price formation, market liquidity, volatility, contagion, and systemic risk. However, the increasing volume, velocity, dimensionality, and complexity of financial data also raise fundamental methodological challenges. Traditional econometric models may struggle to capture the nonlinear dynamics, high dimensionality, temporal dependence, regime changes, and complex interactions that emerge in such environments. These challenges are further amplified by the growing use of machine learning, deep learning, and artificial intelligence in financial markets, including algorithmic trading, portfolio management, forecasting, risk measurement, and financial decision-making.
These developments raise important questions about the interaction between financial-market complexity, Big Data, and AI. How can econometric models be adapted to exploit massive and heterogeneous datasets while preserving interpretability and statistical validity? How can machine-learning and AI methods complement rather than replace structural and econometric approaches? How can we account for model uncertainty, algorithmic interactions, feedback effects, and the potential amplification of market instability induced by increasingly automated trading and decision-making systems? More broadly, how can reliable and robust methodologies be developed to understand financial markets in an environment characterized by increasingly complex data-generating processes, nonlinear dynamics, and rapidly evolving technologies?
Financial market authorities and regulators have also progressively adapted their frameworks to these transformations. Regulatory measures have sought to strengthen financial stability, improve market organization and transparency, monitor algorithmic and high-frequency trading, enhance liquidity and risk management, and address emerging risks associated with increasingly automated and interconnected financial systems. The availability of high-frequency and granular market data, together with advances in econometric modeling, Big Data analytics, and AI, provides new opportunities to evaluate the effectiveness of these regulatory frameworks, identify potential sources of systemic risk, and assess the impact of major economic, financial, and geopolitical shocks.
Against this background, the workshop aims to bring together academics and professionals from economics, finance, econometrics, statistics, data science, and related fields to discuss recent theoretical, methodological, and empirical advances in the analysis of financial markets. Particular attention will be devoted to innovative approaches capable of addressing the increasing complexity of financial data and market dynamics, including nonlinear and nonstationary time-series models, high-frequency and ultra-high-frequency econometrics, regime-switching and structural-break models, network and systemic-risk approaches, machine learning, deep learning, artificial intelligence, generative AI, and Big Data methods.
The workshop will provide a forum for discussing how modern econometric and data-driven methods can contribute to a deeper understanding of financial-market dynamics, including price formation, volatility and liquidity, market efficiency, systemic risk, contagion, forecasting, and financial stability. We particularly welcome contributions that explore the intersection between econometrics and AI, the integration of economic theory with data-driven methods, and the challenges raised by increasingly nonlinear, high-dimensional, and complex financial data-generating processes. By bringing together complementary perspectives from econometrics, finance, statistics, and data science, the workshop seeks to foster new research directions for understanding financial markets in an environment characterized by rapid technological change, increasingly sophisticated data, and evolving sources of economic and financial uncertainty.
Main Topics and Research Areas
The workshop welcomes theoretical, methodological, and empirical contributions addressing the following broad and interconnected research areas:
- Financial Market Dynamics and Nonlinear Econometrics
Financial Market Dynamics – Stock Market Dynamics – Exchange Rate Dynamics – Market Efficiency – Asset Pricing – Volatility Dynamics – Nonlinear Time Series – Nonlinear Dependence – Nonlinear Causality – Threshold and Smooth Transition Models – Regime-Switching and Markov-Switching Models – State-Space Models – Time-Varying Parameter Models – Structural Breaks and Change-Point Detection – Cointegration and Causality – Long-Memory and Fractional Processes – Copula Models and Dependence Structures – Nonlinear Panel Models – Bayesian Econometrics – Nonparametric and Semiparametric Methods. - High-Frequency Econometrics, Market Microstructure and Computational Finance
High-Frequency and Ultra-High-Frequency Econometrics – High-Frequency Trading – Algorithmic Trading – Optimal Trading – Market Microstructure – Order Book Dynamics – Electronic Markets – Market Liquidity and Liquidity Risk – Price Discovery and Price Formation – Microstructure Noise – Realized Volatility – Intraday Dynamics – Computational Finance – Financial Engineering – Simulation and Monte Carlo Methods. - Big Data, Machine Learning and Artificial Intelligence in Finance
Big Data and Financial Markets – High-Dimensional Econometrics – Machine Learning – Deep Learning – Neural Networks – Reinforcement Learning – Artificial Intelligence – Generative AI – Explainable and Interpretable AI – AI-Based Forecasting – Predictive Modeling – AI for Portfolio Management and Trading – AI for Risk Management – Alternative Data – Textual and Sentiment Data – Data-Driven Financial Modeling – Econometrics and AI. - Financial Risk, Systemic Risk and Complex Financial Systems
Financial Risk and Risk Management – Extreme Risk and Tail Risk – Value-at-Risk (VaR) – CoVaR – Expected Shortfall – Extreme Value Theory – Stochastic Volatility – Financial Contagion – Systemic Risk – Financial Networks – Network Econometrics – Complex Financial Systems – Financial Stability – Information Asymmetry – Investor Sentiment and Uncertainty – Financial Bubbles and Crashes. - Financial Crises, Macroeconomic Shocks and Geopolitical Risks
Financial Crises – Financial Market Stress – Pandemics and Financial Markets – Inflation and Financial Markets – Monetary Policy and Central Banking – Interest Rate Dynamics – Macroeconomic Dynamics – Commodity and Energy Markets – Commodity Price Dynamics – Energy Finance – Geopolitical Risks and Financial Markets – Geopolitical Tensions and Financial Market Volatility – Climate and Environmental Risks – Sustainable and Green Finance – Market Regulation and Financial Stability. - Emerging Financial Markets, Digital Assets and Financial Innovation
Cryptocurrencies – Digital Assets – Blockchain – Decentralized Finance (DeFi) – FinTech – Digital and Electronic Markets – Financial Innovation – Behavioral and Experimental Finance – Quantitative and Empirical Finance – Responsible and Social Finance – Sustainable Finance – New Forms of Financial Intermediation.
Contributions combining different methodological and disciplinary perspectives are particularly encouraged, especially those exploring the intersection of financial market dynamics, nonlinear econometrics, macroeconomic dynamics, high-frequency and high-dimensional data, Big Data, artificial intelligence, and complex financial systems. Contributions that bridge econometric theory and financial applications, or that combine traditional econometric approaches with machine learning and AI-based methodologies, are especially welcome.
This international workshop includes plenary sessions, parallel sessions and PhD student sessions.
Submission Process
Authors are invited to submit a full paper, in PDF format and in English, via the workshop website: https://11th-fmnd.eventsadmin.com/Submission or by email to: nd.mm2012@gmail.com.
The complete version of the paper should include the following information:
- Title
- Name(s) of the authors
- Abstract (max 200 words)
- Keywords
- JEL classification
- E-mail address for each author
- Complete address for the corresponding author
Scientific Committee
| Name | Institution | Country |
|---|---|---|
| C. Alexander | University of Sussex | UK |
| H. Amman | University of Amsterdam | The Netherlands |
| Y. Ait-Sahalia | Princeton University | USA |
| W. Barnett | University of Kansas & Center for Financial Stability, New York | USA |
| T. Bollerslev | Duke University | USA |
| D. Bourghelle | IAE Lille University of Management | France |
| R. Bu | The University of Liverpool | UK |
| J. Campbell | Harvard University | USA |
| M. Chauvet | University of California Riverside | USA |
| T. Chordia | Emory University | USA |
| G. Dufrénot | Sciences Po Aix | France |
| Th. Foucault | HEC Paris | France |
| Ph. Franses | Erasmus University | The Netherlands |
| P. Grandin | IAE Lille University of Management | France |
| C. Gresse | Université Paris-Dauphine | France |
| K. Hadri | Queens University Belfast | UK |
| S. Hall | Leicester University | UK |
| J. Hamilton | University of California, San Diego | USA |
| I. Hasan | Fordham University | USA |
| D. Hendry | University of Oxford | UK |
| C. Hsiao | University of South California | USA |
| C. Hommes | University of Amsterdam and Bank of Canada | The Netherlands |
| F. Jawadi | IAE Lille University of Management | France |
| L. Lescourret | ESSEC Business School | France |
| D. Kristensen | University College London & CREATES | UK |
| K. Lansing | Federal Reserve Bank of San Francisco | USA |
| E. Maasoumi | Emory University | USA |
| J. Mairesse | ENSAE-CREST and MIT | France |
| N. Meddahi | Toulouse School of Economics | France |
| B. Mizrach | Rutgers University | USA |
| D. Peel | Lancaster University | UK |
| J. Racine | McMaster University | Canada |
| S. Reitz | University of Kiel | Germany |
| B. Rossi | University of Pompeu Fabra | Spain |
| Ph. Rothman | East Carolina University | USA |
| Ph. Rozin | IAE Lille University of Management | France |
| L. Sarno | University of Cambridge | UK |
| O. Scaillet | University of Geneva and Swiss Finance Institute | Switzerland |
| M. Taylor | Washington University in St Louis | USA |
| T. Teräsvirta | Aarhus University | Denmark |
| E. Theissen | University of Mannheim | Germany |
| H. Tong | London School of Economics | UK |
| R. Tsay | University of Chicago | USA |
| R. Uctum | University of Paris West, & CNRS | France |
| R. Uppal | EDHEC Business School | UK |
| D. Van Dijk | Erasmus University of Rotterdam | The Netherlands |
| R. Valkanov | University California, San Diego | USA |
| J. C. Wu | University of Illinois Urbana-Champaign | USA |
Important Dates
| Deadline for submission | February 28, 2027 |
| Notification of final decision | March 15, 2027 |
| Early bird registration | March 15 – April 15, 2027 |
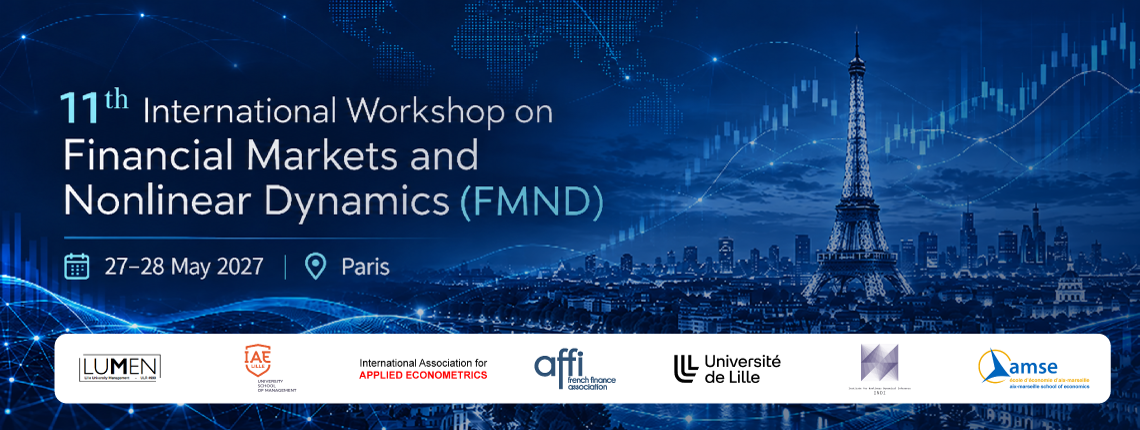
| Dates of the workshop | May 27–28, 2027 |
Publication Opportunities
A selection of papers presented at the 11th FMND workshop will be considered for publication in:
| Journal | Type | Ranking |
|---|---|---|
| Financial Markets, Institutions & Instruments | Section | ABS 3 |
| International Journal of Finance and Economics | Section | ABS 3 |
| Finance | Special issue | ABS 1, FNEGE 2 |
| Macroeconomic Dynamics | Special issue | ABS 2 |
| Studies in Nonlinear Dynamics and Econometrics | Special issue | ABS 2 |