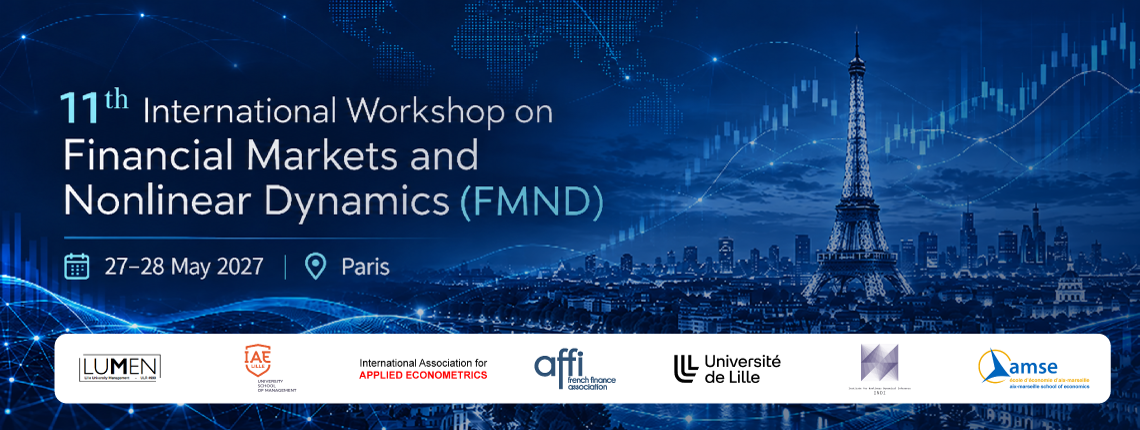
11th International Workshop on Financial Markets and Nonlinear Dynamics (FMND)
Important Note: The submission to the 11th edition of the International Workshop on Financial Markets and Nonlinear Dynamics (FMND), which will be held on May 27-28, 2027, in Paris, is now OPEN.
To make sure that we receive your paper, please also submit it by email to: nd.mm2012@gmail.com
We very much look forward to receiving your papers.
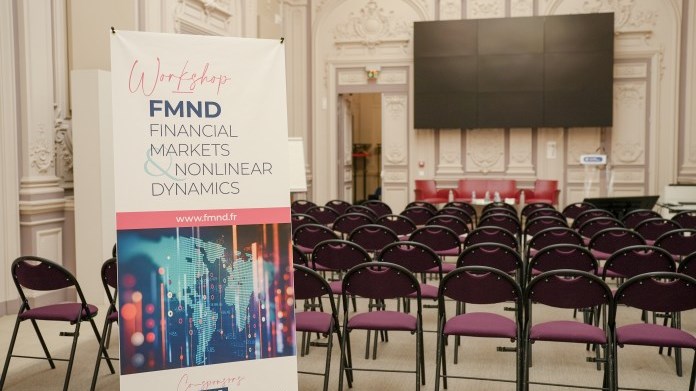
Welcome to the 11th edition of International Workshop in Financial Markets and Nonlinear Dynamics (FMND, May 27-28, 2027 in Paris). We are happy to organize this event, allowing both scholars and finance professionals alike to exchange and confront innovative and thought-provoking ideas about financial market dynamics and nonlinear econometrics.
The Workshop will take place in Paris from 27 to 28 May 2027 with the collaboration of the Internationational Association for Applied Econometrics (IAAE), the Society for Nonlinear Dynamics and Econometrics (SNDE), the Institute for Nonlinear Dynamics Inference (INDI), the French Finance Association (AFFI), the IAE Lille University School of Management (LUMEN), Aix Marseille School of Economics.
| International Association for Applied Econometrics (IAAE) |
| Institute for Nonlinear Dynamical Inference (INDI) |
| French Finance Association (AFFI) |
| IAE Lille University School of Management - LUMEN |
| Aix Marseille School of Economics |
Keynote Speakers
The workshop is pleased to welcome the following distinguished keynote speakers:
| Speaker | Institution |
|---|---|
| Prof. Drew D. Creal | University of Illinois Urbana-Champaign, USA |
| Prof. Whitney Newey | Massachusetts Institute of Technology (MIT), USA |
| Prof. Mark Taylor | Washington University in St. Louis, USA |
| Prof. Jing Cynthia Wu | University of Illinois Urbana-Champaign, USA |
The keynote lectures will bring complementary perspectives on modern econometrics, financial and macroeconomic dynamics, asset pricing, monetary policy, and quantitative methods for analyzing complex financial data. Together, they will highlight key challenges and recent advances in financial econometrics and financial-market analysis.
Organizers
Chairs
| Name | Institution |
|---|---|
| Prof. Gilles Dufrénot | Sciences Po Aix, France |
| Prof. Fredj Jawadi | University of Lille, France |
Co-sponsors
| International Association for Applied Econometrics (IAAE) |
| IAE Lille University School of Management - LUMEN |
Main Topics and Research Areas
The workshop welcomes theoretical, methodological, and empirical contributions addressing the following broad and interconnected research areas:
- Financial Market Dynamics and Nonlinear Econometrics
Financial Market Dynamics – Stock Market Dynamics – Exchange Rate Dynamics – Market Efficiency – Asset Pricing – Volatility Dynamics – Nonlinear Time Series – Nonlinear Dependence – Nonlinear Causality – Threshold and Smooth Transition Models – Regime-Switching and Markov-Switching Models – State-Space Models – Time-Varying Parameter Models – Structural Breaks and Change-Point Detection – Cointegration and Causality – Long-Memory and Fractional Processes – Copula Models and Dependence Structures – Nonlinear Panel Models – Bayesian Econometrics – Nonparametric and Semiparametric Methods. - High-Frequency Econometrics, Market Microstructure and Computational Finance
High-Frequency and Ultra-High-Frequency Econometrics – High-Frequency Trading – Algorithmic Trading – Optimal Trading – Market Microstructure – Order Book Dynamics – Electronic Markets – Market Liquidity and Liquidity Risk – Price Discovery and Price Formation – Microstructure Noise – Realized Volatility – Intraday Dynamics – Computational Finance – Financial Engineering – Simulation and Monte Carlo Methods. - Big Data, Machine Learning and Artificial Intelligence in Finance
Big Data and Financial Markets – High-Dimensional Econometrics – Machine Learning – Deep Learning – Neural Networks – Reinforcement Learning – Artificial Intelligence – Generative AI – Explainable and Interpretable AI – AI-Based Forecasting – Predictive Modeling – AI for Portfolio Management and Trading – AI for Risk Management – Alternative Data – Textual and Sentiment Data – Data-Driven Financial Modeling – Econometrics and AI. - Financial Risk, Systemic Risk and Complex Financial Systems
Financial Risk and Risk Management – Extreme Risk and Tail Risk – Value-at-Risk (VaR) – CoVaR – Expected Shortfall – Extreme Value Theory – Stochastic Volatility – Financial Contagion – Systemic Risk – Financial Networks – Network Econometrics – Complex Financial Systems – Financial Stability – Information Asymmetry – Investor Sentiment and Uncertainty – Financial Bubbles and Crashes. - Financial Crises, Macroeconomic Shocks and Geopolitical Risks
Financial Crises – Financial Market Stress – Pandemics and Financial Markets – Inflation and Financial Markets – Monetary Policy and Central Banking – Interest Rate Dynamics – Macroeconomic Dynamics – Commodity and Energy Markets – Commodity Price Dynamics – Energy Finance – Geopolitical Risks and Financial Markets – Geopolitical Tensions and Financial Market Volatility – Climate and Environmental Risks – Sustainable and Green Finance – Market Regulation and Financial Stability. - Emerging Financial Markets, Digital Assets and Financial Innovation
Cryptocurrencies – Digital Assets – Blockchain – Decentralized Finance (DeFi) – FinTech – Digital and Electronic Markets – Financial Innovation – Behavioral and Experimental Finance – Quantitative and Empirical Finance – Responsible and Social Finance – Sustainable Finance – New Forms of Financial Intermediation.
Contributions combining different methodological and disciplinary perspectives are particularly encouraged, especially those exploring the intersection of financial market dynamics, nonlinear econometrics, macroeconomic dynamics, high-frequency and high-dimensional data, Big Data, artificial intelligence, and complex financial systems. Contributions that bridge econometric theory and financial applications, or that combine traditional econometric approaches with machine learning and AI-based methodologies, are especially welcome.
This international workshop includes plenary sessions, parallel sessions and PhD student sessions.
Submission Process
Authors are invited to submit a full paper, in PDF format and in English, via the workshop website: https://11th-fmnd.eventsadmin.com/Submission or by email to: nd.mm2012@gmail.com.
The complete version of the paper should include the following information:
- Title
- Name(s) of the authors
- Abstract (max 200 words)
- Keywords
- JEL classification
- E-mail address for each author
- Complete address for the corresponding author
Important Dates
| Deadline for submission | February 28, 2027 |
| Notification of final decision | March 15, 2027 |
| Early bird registration | March 15 – April 15, 2027 |
| Dates of the workshop | May 27–28, 2027 |
Publication Opportunities
A selection of papers presented at the 11th FMND workshop will be considered for publication in:
| Journal | Type | Ranking |
|---|---|---|
| Financial Markets, Institutions & Instruments | Section | ABS 3 |
| International Journal of Finance and Economics | Section | ABS 3 |
| Finance | Special issue | ABS 1, FNEGE 2 |
| Macroeconomic Dynamics | Special issue | ABS 2 |
| Studies in Nonlinear Dynamics and Econometrics | Special issue | ABS 2 |